Comparing Luxury Real Estate Holdings: Arnault and Bieber
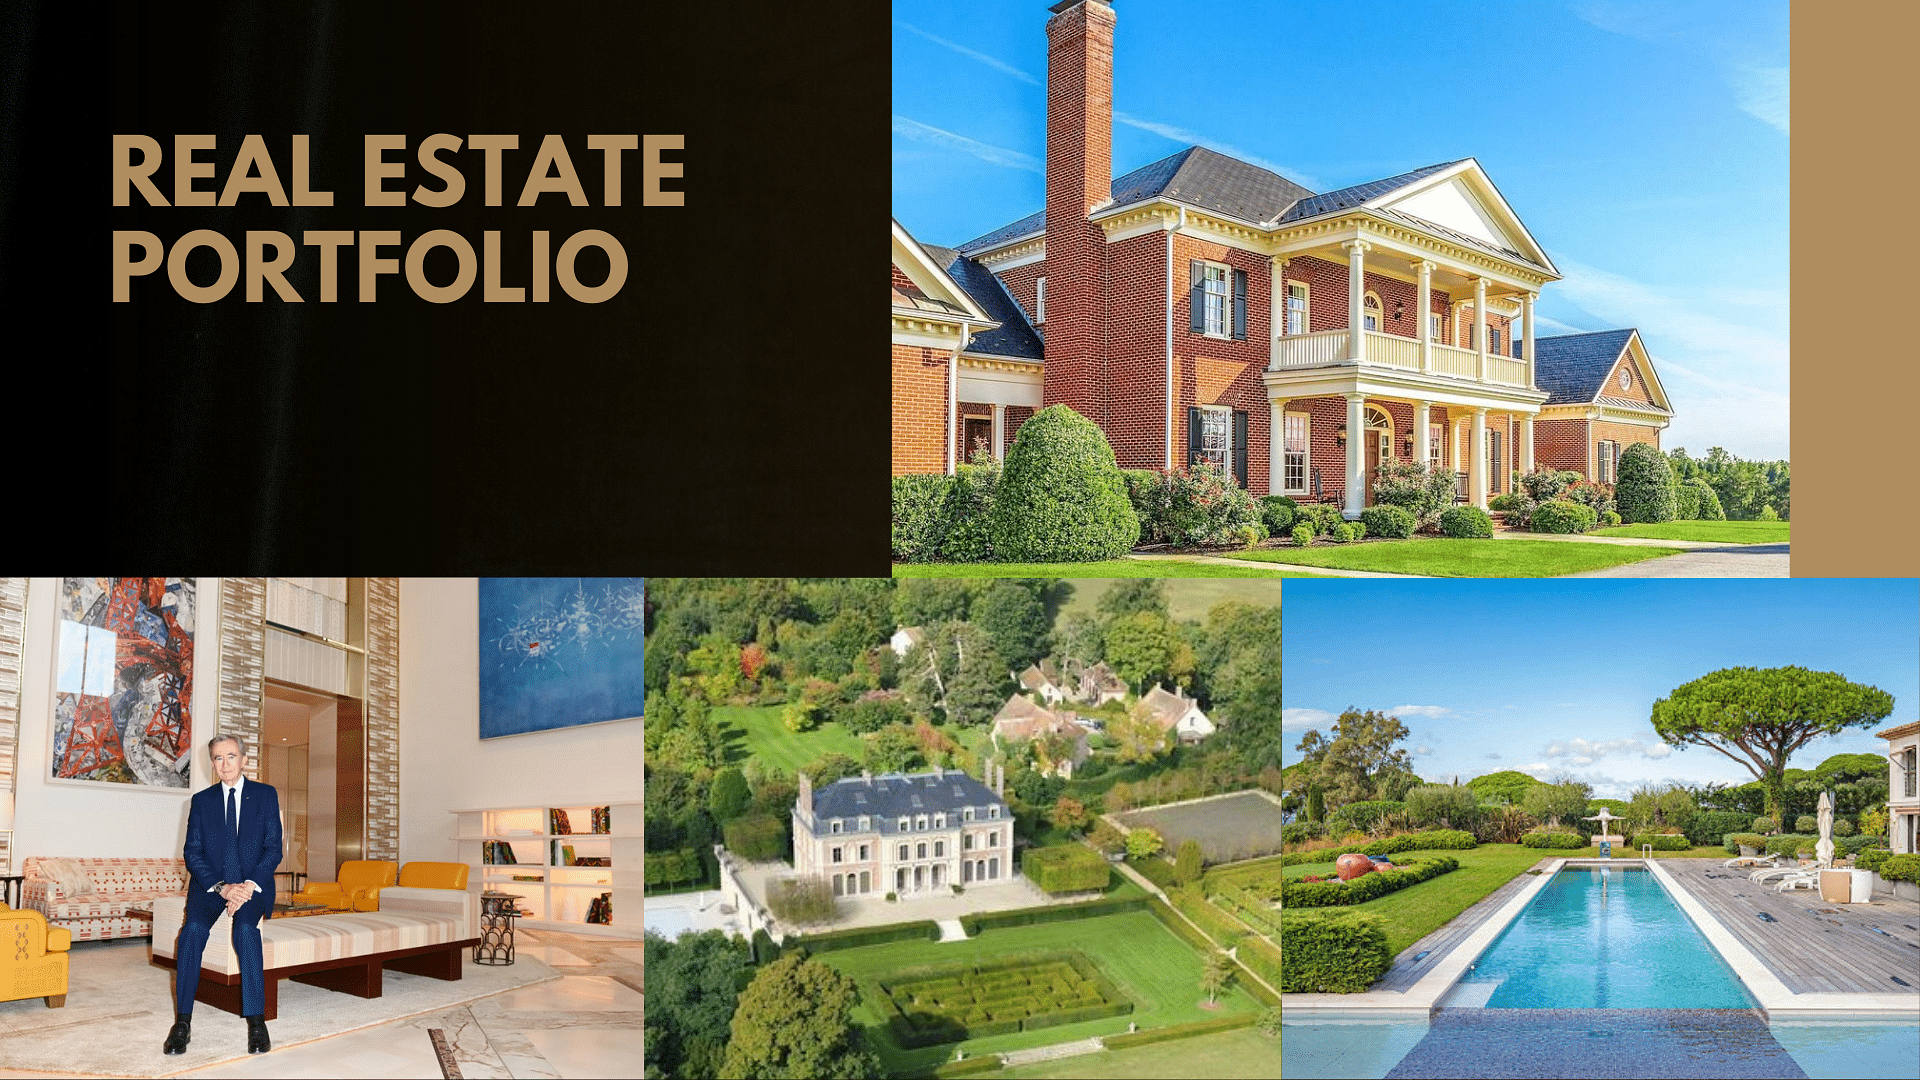
The real estate portfolio of Bernard Arnault versus Justin Bieber is less about direct competition and more about understanding two completely different models of wealth display through property. I've spent years tracking luxury real estate transactions across multiple continents, and comparing these two portfolios reveals something most people miss. It's not a question of who has more money or more square footage. It's a question of strategy, geography, and the underlying purpose each portfolio serves. Arnault's holdings are concentrated, institutional, and almost entirely European. His primary residence sits in Paris, though the exact address is deliberately vague in public records. He owns significant stakes in French châteaux and properties that have been in family hands or acquired through LVMH's broader network. The portfolio tends to favor assets that hold value through decades rather than quarters. These are stone-and-mortar holdings in places like Deauville, Parisian avenues, and various European estates that function more like private museums than casual residences. Bieber's portfolio, on the other hand, reads like a diversification play across markets that generate both personal enjoyment and speculative upside. He purchased a $12.8 million estate in Beverly Hills around 2019, which he later sold at a significant profit. He also owns property in Miami, Nashville, and has been linked to purchases in the Hamptons and Malibu. Each of these markets operates on different cycles and different regulatory frameworks. A Toronto investor trying to navigate a California transaction without understanding non-resident withholding taxes will lose money regardless of how good the deal looks on paper.
The Practical Difference in Strategy
Arnault treats real estate as a permanent capital allocation. These properties are part of a broader wealth preservation framework that includes art, collectibles, and operational business assets. There's very little turnover in his portfolio because selling a European estate of that caliber takes time, attracts unwanted attention, and often results in a value loss relative to the emotional and strategic premium placed on holding. Bieber's approach is far more transactional. He buys, he renovates, he sells. That is the model that made his portfolio notable in the first place. The Beverly Hills flip alone demonstrated an understanding of market timing that most retail investors never develop. The challenge there is scaling that approach. One successful flip does not mean you can replicate it three times in a row. Market conditions shift, renovation costs spiral, and the margin between a gain and a loss in those transactions often comes down to a single inspection finding you missed.
What You Actually Need to Know Before Trying This
If you are trying to build a portfolio model along either of these lines, the first thing to understand is that the entry cost for competitive real estate in Beverly Hills, Malibu, or central Paris is not just high. It is exclusionary by design. Properties at this tier rarely appear on public MLS listings. They move through off-market channels, private broker networks, and sometimes direct developer negotiations before anyone sees a flyer. The reason most people cannot compete is not a lack of capital alone. It is a lack of access to the distribution channels where these transactions actually happen. Another thing nobody talks about is the tax structure. American citizens buying in France face dual reporting obligations. French non-residents pay the impôt sur la fortune immobilière on French-sited real estate, and the US still taxes worldwide income regardless. The interaction between these two systems creates a filing complexity that most tax preparers handling standard returns are not equipped to manage. I had a client who bought a property in Cannes through an LLC structure I helped set up, and we still spent roughly sixty hours in the first year reconciling foreign tax credit elections between the US and French authorities. That is before any ongoing annual compliance.
Get the Full Details
Market Cycle Awareness Is Non-Negotiable
The Beverly Hills market moved through a three-year boom phase and then corrected sharply in 2022 and 2023. Properties that sold for $15 million in early 2021 were still sitting on the market at $12.5 million two years later with minimal offers. Meanwhile, Miami absorbed that capital flow differently. The same dollars that left California moved into South Florida and kept pushing prices there higher well into 2024. A portfolio that only holds California luxury real estate in 2023 was underperforming by a wide margin compared to one that had geographic flexibility. Arnault's portfolio benefits from geographic concentration in Europe precisely because European luxury real estate cycles do not perfectly correlate with American ones. That is not a coincidence. It is structural. French property, particularly in the Côte d'Azur and Parisian districts, moves slower and responds differently to interest rate changes than Los Angeles or Miami. The tradeoff is liquidity. You can sell a Miami condo in weeks. You might be looking at six to eighteen months to find a buyer for a Parisian mansion at the right price.
Why This Comparison Matters for Regular Investors
The Arnault versus Bieber real estate portfolio comparison is not useful if you are trying to copy either model directly. Neither is replicable at a normal income level. What it does show is the difference between a preservation strategy and a growth strategy, and those two approaches require fundamentally different skill sets. Preservation demands patience, tax expertise, and long-term holding capacity. Growth demands market timing, renovation knowledge, and the ability to move quickly when opportunities appear. The biggest mistake I see is when investors try to run both strategies simultaneously. They buy a property expecting to flip it while also treating it like a long-term hold. That confusion leads to indecision during critical windows. You either sell too early and leave money on the table or hold too long and watch carrying costs eat your margin. I once watched a client hold a renovated property in West Hollywood for fourteen months past his target exit date because he could not decide between selling or renting it out. He ended up paying nearly $40,000 in carrying costs and property management fees that wiped out what would have been a clean exit.
The Numbers Nobody Shares Publicly
Arnault's total real estate value is estimated in the billions, but the actual figures are opaque. LVMH's corporate holdings are separate from personal ones, and personal holdings are shielded by trusts and foundation structures that make accurate valuation nearly impossible from the outside. What is known is that his properties generate minimal direct rental income. Their value proposition is holding power, not cash flow. Bieber's portfolio is similarly opaque but follows a different public pattern. His known transactions total roughly $25 to $35 million across all purchases and sales combined. The gross numbers sound smaller, but the turnover rate and profit percentages tell a different story. A $2 million gain on a $12 million flip is an 18 percent return. That is not a bad number in any asset class, especially when achieved over a twelve-to-eighteen-month holding period.
What Happens When Markets Reverse
The hard truth about high-end real estate portfolios is that they look brilliant during upward cycles and reveal their weaknesses during corrections. The Beverly Hills sale Bieber completed in 2023 happened in a market where inventory was elevated and buyers were cautious. Selling at a profit in that environment required a buyer who was willing to overlook certain issues or a seller who could hold until the right offer appeared. Most people do not have that option. They need to sell and they sell at whatever the market will give them. Arnault's portfolio is insulated from this problem largely because he does not need to sell. That is the fundamental advantage of institutional-grade holdings with zero leverage pressure. When I worked on a acquisition for a client who tried to mirror an Arnault-style hold, we discovered too late that his financing had a balloon payment due in twenty-four months. The property could not be sold quickly enough without taking a significant loss. The strategy looked sound in theory and fell apart entirely in practice because of a financing detail that should have been checked first.
Bottom Line
The Bernard Arnault versus Justin Bieber real estate portfolio comparison ultimately shows two valid approaches operating at different scales with different constraints. One is built for permanence and wealth preservation. The other is built for transactional gains and market participation. Understanding which model fits your actual situation, liquidity needs, and risk tolerance matters more than trying to replicate either one directly. Both require specialized knowledge, access to off-market deals, and the ability to navigate complex tax structures across jurisdictions. Without those elements, the comparison is just entertainment rather than a usable framework.